Why is Black Friday won in Q1, not Q4?
Top-quartile brands don't switch on upper-funnel spend for peak, they hold it above 20% all year round. Here's the client data behind why Q4 is won early.
All
Learn More

A marketing source of truth is a written agreement between marketing and finance. Here are the five parts that get finance to sign off and teams to use it.
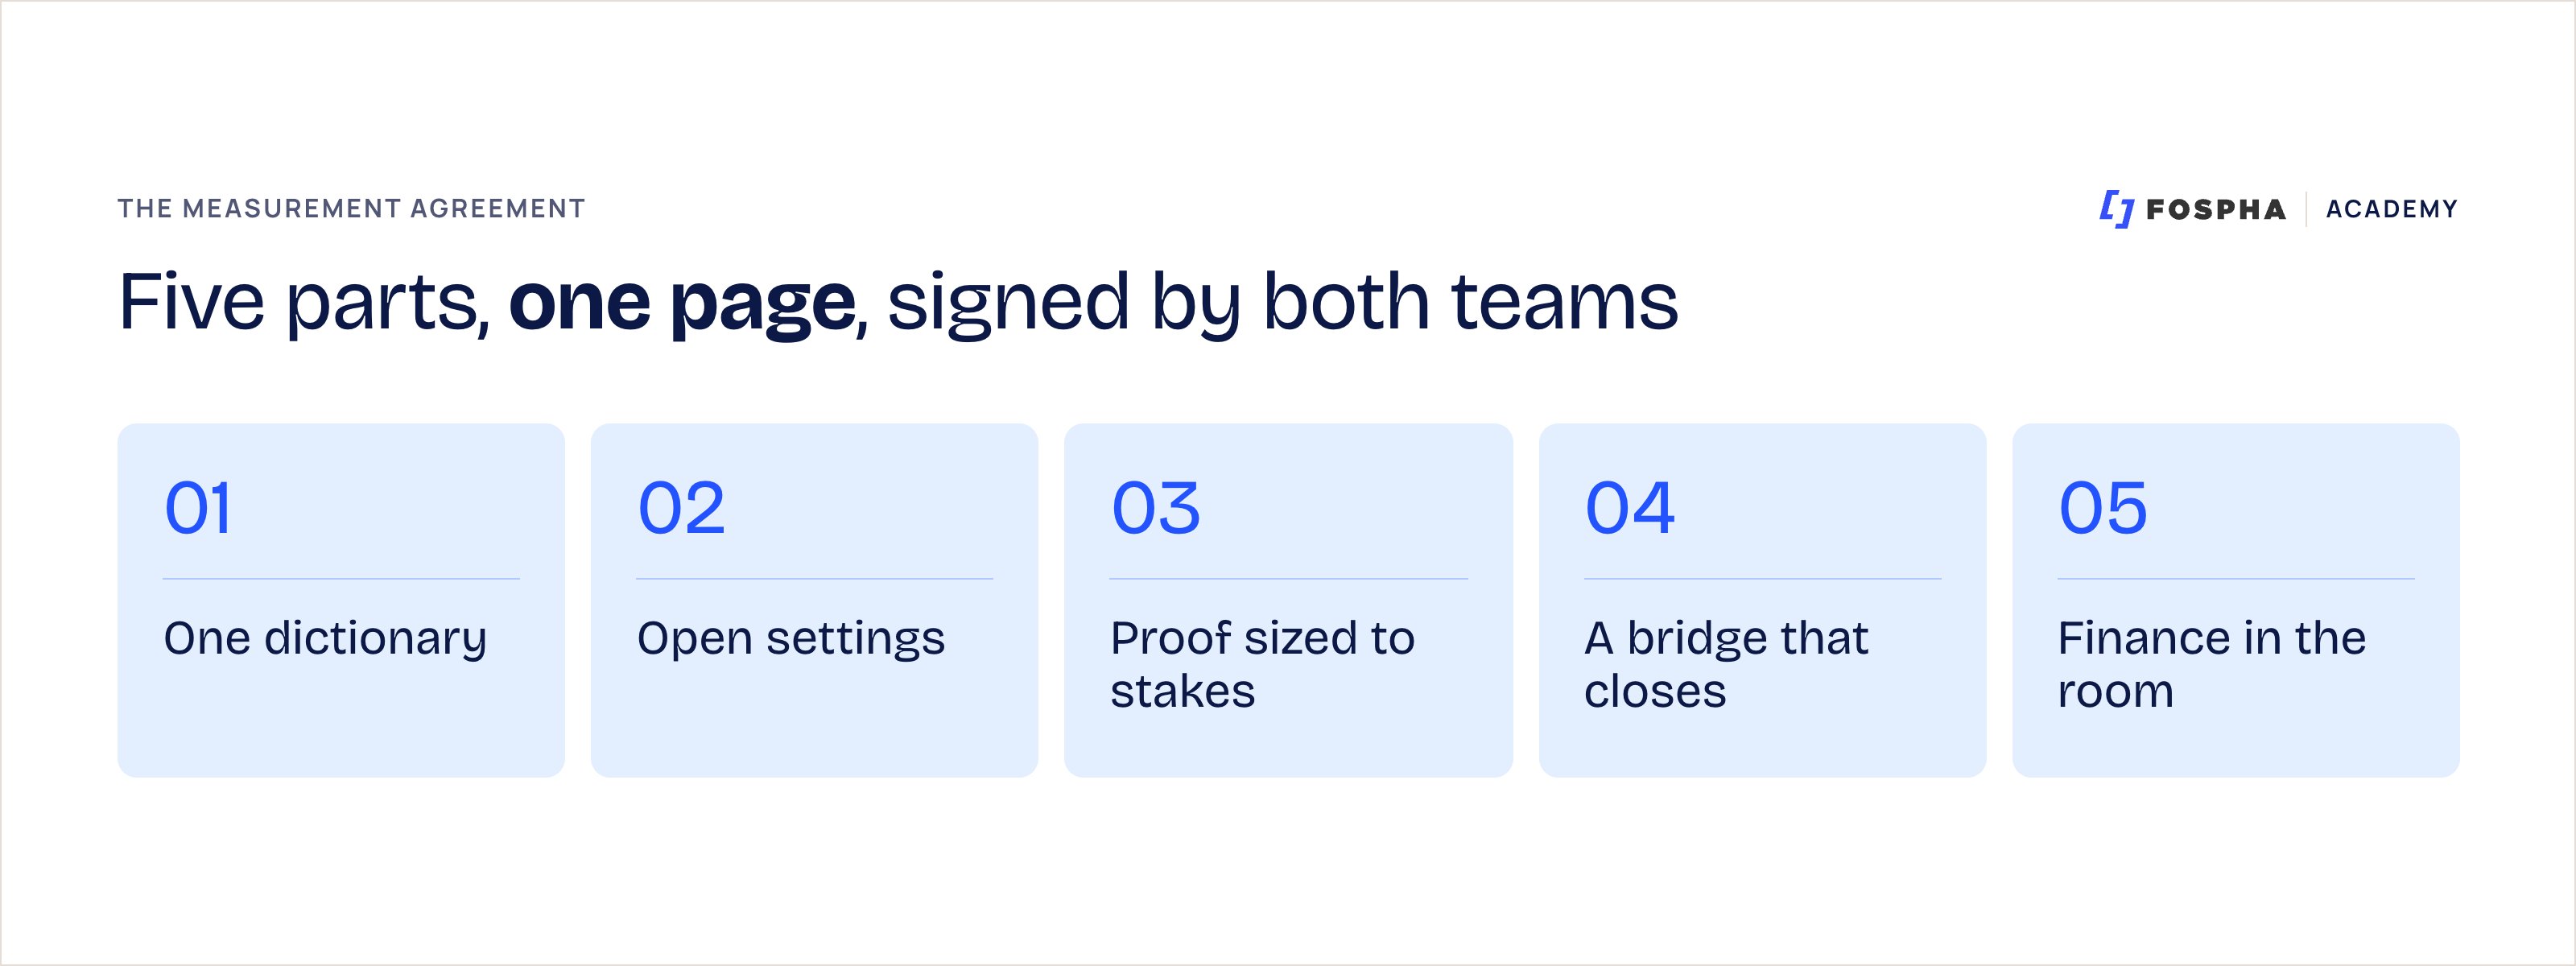
A marketing source of truth is the one set of numbers marketing and finance both agree to run on. Building it takes a written agreement with five parts: a shared dictionary of metrics, open settings, proof sized to the stakes, a revenue bridge that closes, and finance in the room before budgets are set.
A single set of numbers stops teams arguing over conflicting figures and aligns them on real business impact. Getting there is harder than it sounds. Most source-of-truth projects fail for one of two reasons. Finance doesn’t trust the number, or the team can’t run the week on it. A real source of truth passes both tests. Finance can verify it, and marketing can use it every Monday morning.
The first test gets the attention. In a 2026 survey of 1,397 senior marketing and finance executives, Bain & Company and Google found that more than half of both groups see direct revenue impact as the most important way for marketing to earn standing with finance. Yet only 41% of the marketers surveyed felt equipped to tie their performance to business outcomes.
The second test gets less, and it’s where we see enterprise teams stall. Even brands with a strong marketing mix model (MMM) and a test program keep making their weekly calls from last-click and platform reports, because those update daily and everyone knows how to read them. A number that’s trusted in the quarterly review but ignored on Monday isn’t a source of truth.
Both tests come down to a written agreement. Bain found that leaders set a measurement framework shared by marketing and finance before budgets are allocated. Companies with strong marketing and finance relationships were almost 1.5 times more likely to lead their sectors, though that’s a correlation, not proof of cause.
Here’s the five-part agreement we’d put in place:
Write down every metric once, with one definition, one data source and one owner. Keep the list short. We’d cap it at ten metrics, because a long list is a sign nobody has decided what matters.
The test is simple. If two people can’t define a metric in a single sentence, it isn’t ready for the agreement. Retire a metric rather than redefining it, and date every change.
Start with the words that cause the most arguments. “Revenue” can mean gross sales, sales after returns, or what the ledger books. “New customer” can mean a first order on the site or a first order ever. “Spend” can include or exclude agency fees and tax. Retail brands face one more decision. Does revenue include retailer and marketplace sales, and does it count at sell-through or at wholesale shipment?
Every number in the agreement should arrive with its settings, and with how it differs from last click. Finance trusts what it can question. A number nobody can interrogate gets overruled in the room, however good the model behind it.
Keep two logs.
Both logs work with any measurement method, whether MMM, multi-touch attribution, incrementality tests or platform reports. Our lesson on triangulating the three shows how they fit together.
Decide in advance how much evidence each kind of decision needs. The more expensive a mistake is to reverse, the more independent the evidence should be. These thresholds are examples, so set your own.
“Independent evidence” can be a model, an incrementality test, a natural experiment or a historical comparison. The agreement sets the bar, and any method that clears it counts. Platform reporting keeps its job in daily optimization inside each platform. The ladder applies to decisions that cross platforms or budgets.
Every month, walk from what the platforms claim to what finance booked, and label every gap. The bar is that the bridge closes. A bridge with a large “unexplained” line isn’t finished, and the unexplained line should shrink every month.
The numbers differ for ordinary reasons. Each platform counts credit under its own rules and windows, so claims can overlap. Gross sales differ from net sales after returns and discounts. And for retail brands, a lot of revenue happens where the platforms can’t see it, on marketplaces, at retailers and in stores.
In this example the platforms claimed $1.30M, more than the $1.05M of DTC net revenue finance booked. Meanwhile $0.55M of marketplace revenue that marketing may have influenced sits outside the platforms’ view.
When the bridge doesn’t close, settle the tie-break rule before the argument starts. Finance’s booked revenue sets the total, and marketing’s view explains how it splits across channels. Then investigate in a fixed order:
Bring finance into planning before budgets and targets are set, and agree how often each number refreshes. In the Bain and Google survey, leaders lock their metrics before campaigns begin, and a strong chief marketing officer (CMO) and chief financial officer (CFO) relationship correlated with almost two times higher revenue growth. Again, that’s correlation from self-reported data.
In practice, hold a standing monthly session with named attendees from both teams, and put a sign-off line in the agreement. Name one owner on each side. Marketing owns the measurement view, and finance owns the revenue total.
Then match the rhythm to the decisions. If the agreed view only refreshes monthly, the team will keep running the week on whatever updates daily. Decide how often each metric needs to refresh, and which view is the default in the Monday trading meeting.
Treat the whole thing as a change program, not a reporting project. Expect the first quarter to feel slower, and train the people who’ll live in it. For how to order a plan from the profit and loss (P&L) statement, see our lesson on starting every marketing plan from the P&L.
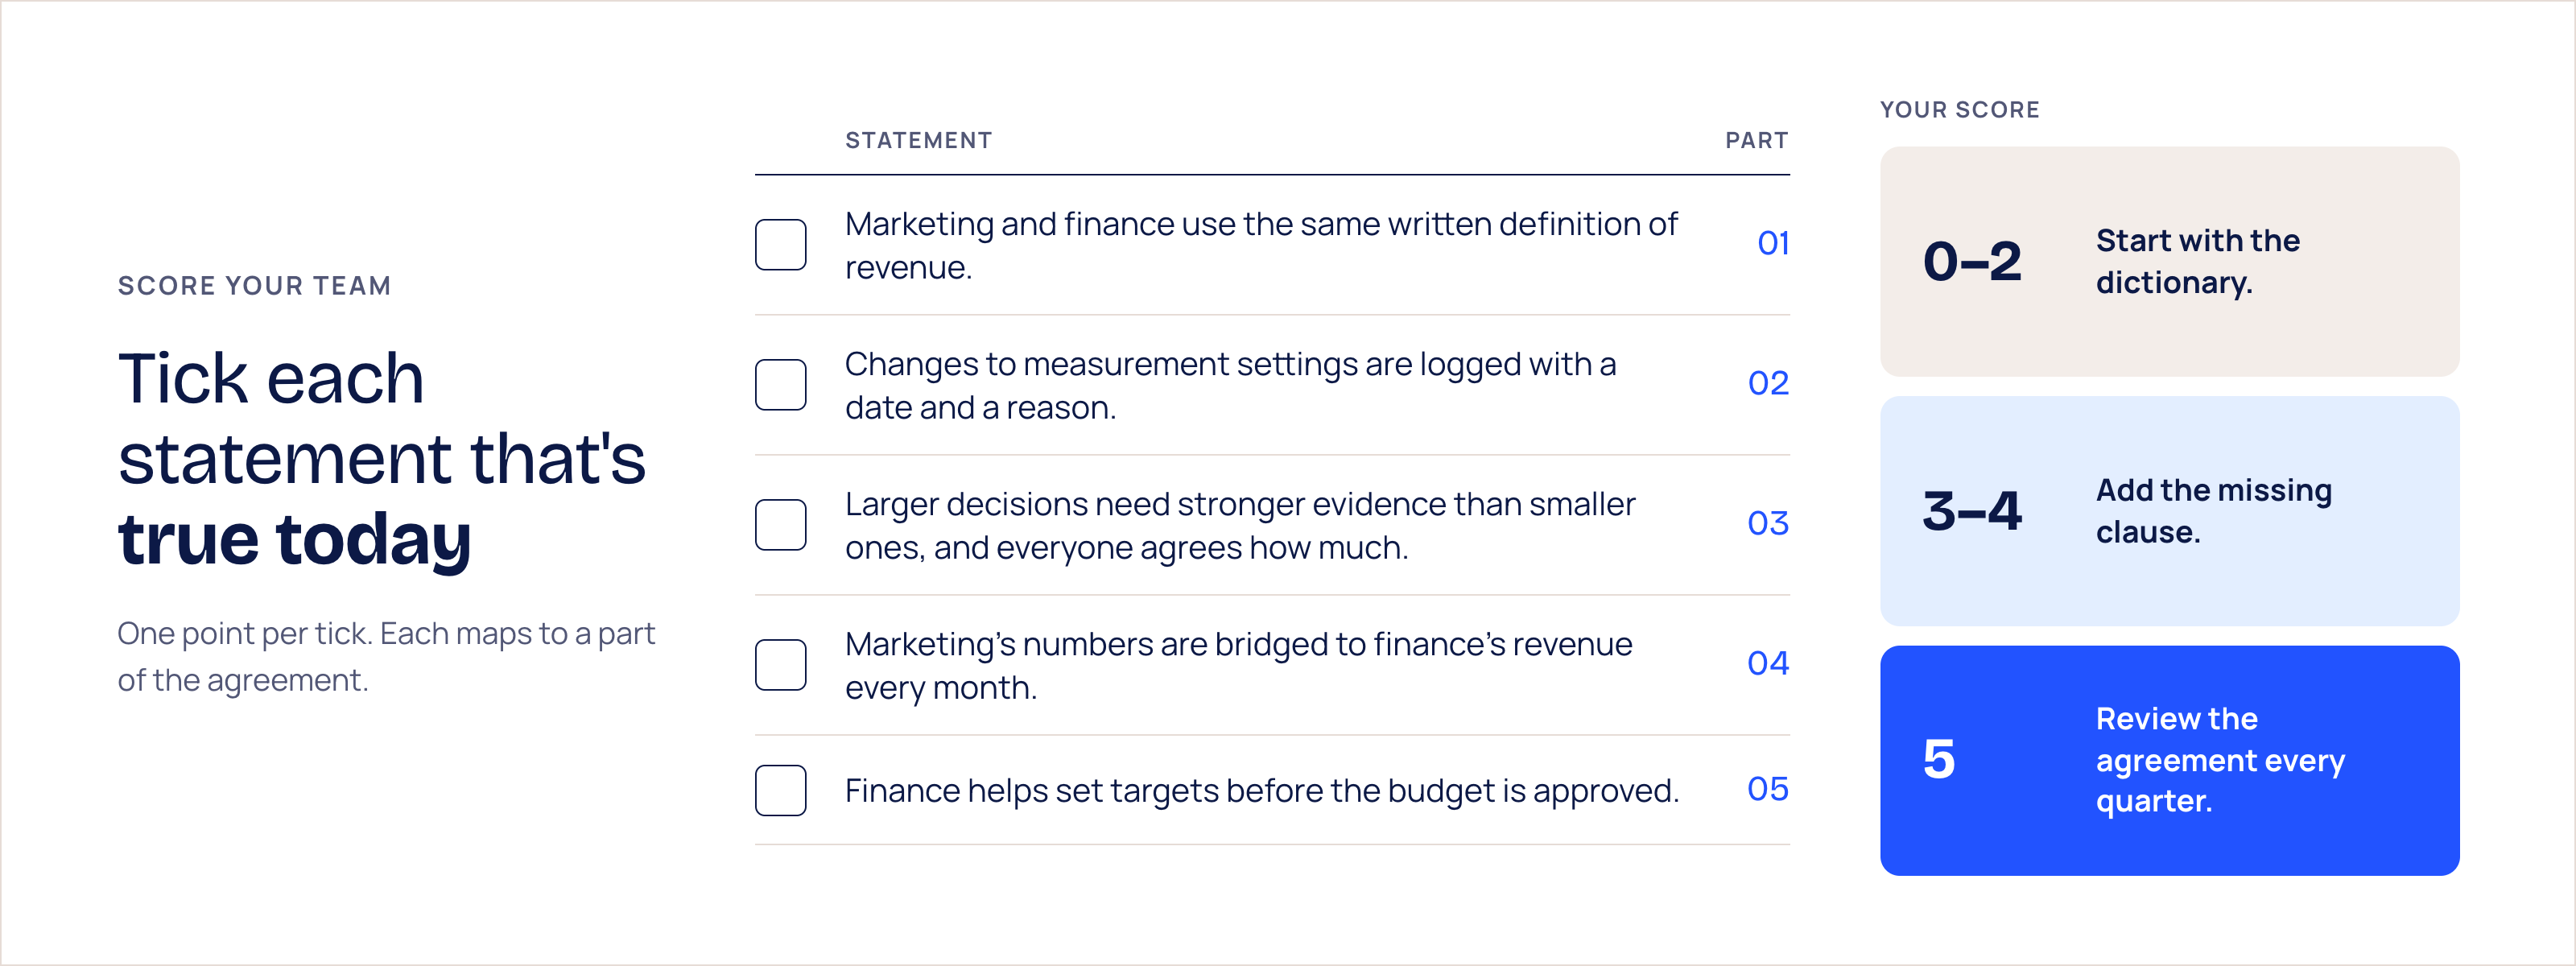
Tick each statement that’s true today.
1. Marketing and finance use the same written definition of revenue.
2. Changes to measurement settings are logged with a date and a reason.
3. Larger decisions need stronger evidence than smaller ones, and everyone agrees how much.
4. Marketing’s numbers are bridged to finance’s revenue every month.
5. Finance helps set targets before the budget is approved.
0 to 2: start with the dictionary. 3 to 4: add the missing clause. 5: review the agreement every quarter.
A good measurement system gives you the numbers. A great measurement system gives every team numbers they all agree on and run the week on. The agreement is how you get there. Build one dictionary, keep the settings open, size the proof to the stakes, bridge to finance’s revenue, and give finance a seat.
Measuring marketing impact beyond your DTC website
What do we do when marketing’s numbers and finance’s revenue disagree?
Follow the tie-break rule. Finance’s booked revenue sets the total, and you investigate definitions, timing, data and settings in that order. Until it’s resolved, apply the stronger evidence tier to any decision it touches.
Who should own the source of truth?
Both teams, with clear halves. Marketing owns the measurement view and the settings log. Finance owns the revenue total and signs off on definitions.
Does a source of truth mean using one measurement method?
No. The agreement sets how much evidence each decision needs. Any method, or combination of methods, that meets the bar can supply it.
Which revenue should a retail brand reconcile to?
The revenue finance books, defined in writing. Decide whether it includes retailer and marketplace sales, and when each counts. Then bridge the part the ad platforms can see, and list the rest separately.